Can Bangladesh make better use of its zakat money?
Earlier this year, the Prime Minister instructed his government to create a properly organised zakat system. To accomplish this, the Zakat Board under the Ministry of Religious Affairs is to be restructured to include experts from several disciplines, bringing in scholars, economists and officials.
The scope of the undertaking is ambitious: Tk 1 lakh a year for some 500,000 poor families, delivered in phases, with the expectation that they will achieve financial independence within ten to fifteen years. Simple arithmetic shows how large the commitment is. At Tk 1 lakh (Tk 100,000) per family for 500,000 families, the programme needs Tk 5,000 crore (Tk 50 billion) a year. Earlier studies place the country’s entire annual zakat pool at Tk 20,000–25,000 crore. The new programme would need roughly a fifth to a quarter of all zakat given in Bangladesh.
To put the scale in perspective, the government’s zakat fund, operated by the Islamic Foundation, received Tk 10.21 crore in FY2022-23. The gap between the existing distribution structure and the proposed programme is roughly five-hundredfold.
This gap deserves more attention because the usual response to it is the wrong one. Many people immediately call for more zakat, through more sermons, more Ramadan appeals and more reminders of the obligation. Bangladeshis are not ungenerous. The sheer size of the annual zakat pool, Tk 20,000–25,000 crore, shows that they give. They may well be able to give more, but the binding constraint facing the country is how zakat is distributed, while the quantity collected matters far less. A large part of this problem can be stated precisely: of the eight categories of expenditure established by the Quran, Bangladesh currently uses only six.
Verse 60 of Surah al-Tawbah names them: the poor, the needy, those employed to administer zakat, those whose hearts are to be reconciled, the freeing of slaves, debtors, fi sabilillah (“for the sake of Allah”) and ibn al-sabil, the stranded traveller. The first six are well known and used in various ways throughout Bangladesh. The last two have been virtually inactive, and they are perhaps the two that best describe the emergencies Bangladesh faces today.
The son of the road
Ibn al-sabil literally means “son of the road”: a traveller who is cut off from his possessions and stranded away from home. The majority of classical jurists considered such travellers eligible for zakat even if they were wealthy, and the reasoning behind that ruling matters more than the ruling itself. Having property and being able to access it are different things. A man may own land and a bank account and, through circumstances beyond his control, be unable to reach either. For the purposes of relief, that man is poor.
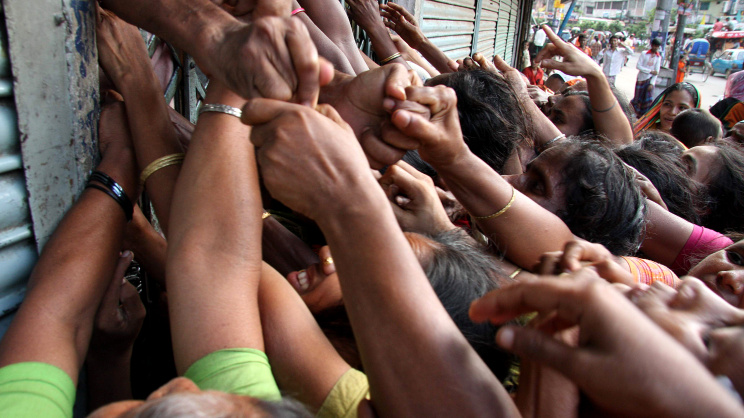
This is not a hypothetical situation in Bangladesh today. The 1.2 million Rohingya refugees in Cox’s Bazar are separated from their land and property by a border they cannot cross. The International Organization for Migration (IOM) published its first nationwide assessment in December 2025, counting 4,955,527 people internally displaced by floods, cyclones and riverbank erosion. A farmer who has lost his homestead to the Jamuna still holds title to land that no longer exists. In the terms of fiqh, he is exactly the traveller whom Imam al-Tabari and Ibn Zayd described when they said the wayfarer’s right attaches the moment he is separated from his wealth.
Some Hanafi imams extended ibn al-sabil to anyone absent from his property and unable to use it, including the merchant whose receivables have become unrecoverable. Certain Hanbali scholars included those who take refuge in streets and alleys. Rashid Rida, author of Tafsir al-Manar, argued that foundling children should also qualify, noting that earlier commentators had passed over them only because such children were rare in their day.
Some Hanafi imams extended ibn al-sabil to anyone absent from his property and unable to use it, including the merchant whose receivables have become unrecoverable. Certain Hanbali scholars included those who take refuge in streets and alleys. Rashid Rida, author of Tafsir al-Manar, argued that foundling children should also qualify, noting that earlier commentators had passed over them only because such children were rare in their day. Refugees, the internally displaced, the involuntarily illiquid, street children and the rootless: a whole modern class of social welfare recipients fits within a head written in seventh-century vocabulary.
Nor was this ever mere theory. Ibn Sa’d records that Caliph Umar ibn al-Khattab set up a building, the dar al-daqiq, or house of flour, stocked with flour, dates and water for impoverished travellers. He made similar provision along the route between Makkah and Madinah. The directive that Imam Ibn Shihab al-Zuhri prepared at the request of Umar ibn Abd al-Aziz went further. It directed that the ibn al-sabil share be apportioned according to the number of travellers using each route and that a traveller without accommodation be placed with reliable households in the area. Proportional allocation based on assessed need, with a defined delivery mechanism, amounted to budgetary planning thirteen centuries early. It is a higher standard of administration than the one we apply today.
The harder argument
Fi sabilillah is more contentious. Most jurists of the four major schools limited it to jihad and its ancillary activities, and readers should recognise that this was the prevailing view for a long time. Against this position stood Imam al-Razi, Rashid Rida, Shaykh Mahmud Shaltut, Sayyid Sabiq and Yusuf al-Qaradawi, who read the phrase in its root lexical sense, the path by which one approaches God, and applied it to works of public good more generally. The broader interpretation is no modern construct in traditional dress. It has institutional support. The eighth session of the Islamic Fiqh Academy in Makkah (1405 AH) and the First Symposium on Contemporary Issues of Zakat in Cairo (1409 AH/1988 CE) each ruled that da’wah (proselytisation), education and research fall within fi sabilillah.
The objection deserves a fair hearing, and it has two prongs. The Hanafis consider tamlik, the transfer of ownership to an identifiable recipient, an essential component of zakat, so spending on an institution that no one owns does not meet this requirement. The word innama at the opening of the verse also restricts the categories to eight.
If one reads fi sabilillah expansively, one effectively nullifies the restriction imposed by the other seven categories. This is no pedantic worry. When a head can fund everything, it ends up funding nothing in particular, and the share that gets squeezed is invariably that of the poor.
There are responses to these objections. In the four heads that the verse introduces with the particle fi (slaves, debtors, the way of Allah and the wayfarer), no transfer of ownership to an individual is required, and the grammatical construction appears to be doing deliberate work. Scholars who allow zakat to pay the debts of a deceased person have already conceded an exemption from tamlik, since a dead man possesses nothing. Also, when the state or an accredited institution accepts zakat, it receives it as an agent for those who qualify, which is itself a recognised form of possession.
So zakat can be expended in accordance with a broader definition, and what remains is the question of discipline. Anyone who accepts a broader definition must simultaneously acknowledge the need for tight accounting standards for each head and restrictive allocation ceilings. Without such discipline, the objections are valid.
What would the head fund?
The actual list of potential beneficiaries should be intentionally brief: higher education and vocational training for students from low-income backgrounds; research capacity and trained personnel in areas related to Islamic economics and Shariah audit; and stipends for teachers at reputable educational institutions focused on religion and social education, provided that they cannot otherwise generate income because they are engaged in teaching.
Rashid Rida himself added this proviso, and he refused payment to any scholar who could afford to teach without it, a discipline that our own institutions would likely find difficult to implement. Unless an explicit and auditable schedule such as the one above is articulated, within several budget cycles the head will degenerate into a shelter for administrative overheads.
Why does the zakat fund collect only Tk 10 crore?
The central riddle can now be addressed. Why does Bangladesh collect only Tk 10 crore annually through its national zakat fund?
There is no theological basis for this. It is explained by institutional trust issues and entirely rational behaviour. Because of a lack of transparency regarding distribution channels, donors are unable to determine where the money went, who received it or how much of it was consumed by administrative costs. There are no audited and published financial statements, there is no separate reporting or accounting by head, and there is no independent monitoring agency. Consequently, an observant Bangladeshi makes direct donations to relatives, neighbours or the madrasa down the lane, where at least he can observe the results with his own eyes. Such behaviour does not represent superstition concerning government. It represents a rational reaction to asymmetric information.
Legislation also contributes to this issue. The Zakat Fund Management Act 2023 (which repealed the Zakat Fund Ordinance 1982) created a 13-member Zakat Board headed by the Minister for Religious Affairs and consisting of five scholars chosen by the government, officials from three ministries, two representatives of trade bodies and the Director General of the Islamic Foundation.
Legislation also contributes to this issue. The Zakat Fund Management Act 2023 (which repealed the Zakat Fund Ordinance 1982) created a 13-member Zakat Board headed by the Minister for Religious Affairs and consisting of five scholars chosen by the government, officials from three ministries, two representatives of trade bodies and the Director General of the Islamic Foundation. The Board is required to meet at least twice a year. This is clearly not an independent entity. Whatever else it provides, it cannot assure a donor that his zakat will be protected from political interference, and the government’s own review has acknowledged past examples in which funds were diverted to vested interests. The current proposal to revise the 2023 Act and bring economists onto the Board does improve on the existing legislation. But adding expertise to an entity headed by a sitting minister does little to answer what a donor really wants to know.
There is a legitimate counter-argument here, and it should not be dismissed lightly. Decentralised giving has inherent advantages: it is immediate, there are virtually no overhead costs associated with it, and it builds upon local knowledge that no centralised database can replace. A neighbour knows which household lost its wage earner last month. A national board does not. Advocates against collecting zakat nationally are not simply obstructionist. They are protecting a method of disbursing money that, although informal, reaches people rapidly. So advocates for collecting zakat nationally must argue on merit why an institution that donors trust should collect it, and that argument is specific: the two dormant heads are precisely the ones individual donors cannot adequately serve. No individual donor can finance a displacement response, a research programme or a scholarship scheme alone. Programmes such as these require pooling, which requires an institution that donors believe to be trustworthy. Ideally, donors want a trusted institution alongside private giving, not a state monopoly over it.

What others did
Malaysia and Indonesia offer the obvious comparisons, though the lessons from them are narrower than people usually suggest.
Malaysia’s success is one of taxation and owes little to rhetoric. Zakat payments are treated by Malaysia’s Inland Revenue Board (IRB) as rebates against taxes charged. They reduce the tax liability itself, up to the full amount of tax due, which is different from a deduction from taxable income. The design of this single rule converts zakat from a private charitable activity competing with the tax obligation into an alternative method of fulfilling part of that obligation, and this explains much of what is generally attributed to piety as the reason for the high rate of zakat collection.
Indonesia’s achievement is informational. Its national zakat agency, BAZNAS, reports national zakat collection every six months against a previously announced annual target: zakat, infaq and sadaqah collections of approximately IDR 27 trillion in the first half of 2025, against an annual target of IDR 50 trillion. BAZNAS also reports transparently when there are declines in collection, such as the slight one that occurred that year. A contributor can verify how much money was collected. That is the complete system.
At one point, Bangladesh too had this tax incentive and has largely forgotten about it. Section 13 of the old Zakat Fund Ordinance 1982 provided that no income tax would be payable on amounts paid to the Zakat Fund as zakat. A similar type of exemption, modernised into a rebate like the one used in Malaysia and administered jointly by the National Board of Revenue (NBR) and the Zakat Board, would likely contribute significantly more to zakat collection than all possible appeals. It would also provide the additional benefit of an audit trail, because any rebate would have to be documented before it could be claimed.
What should be done
The order of events is not difficult to understand, nor does it require everyone to agree on the fi sabilillah question before proceeding.
In the short term, Bangladesh’s national Zakat Fund should be required to publish audited annual financial statements, separately disclosing expenditure under each of the eight heads as well as administrative expenditure. No new law is needed for this, only a decision.
In the medium term, the 2023 Act should be amended to create an independent agency outside both the direct supervision of the Ministry of Religious Affairs and the administration of government revenue. It should have a non-ministerial chairman, fixed terms, published minutes and an independent auditor.
In the medium term, the 2023 Act should be amended to create an independent agency outside both the direct supervision of the Ministry of Religious Affairs and the administration of government revenue. It should have a non-ministerial chairman, fixed terms, published minutes and an independent auditor. The tax treatment of zakat payments made to the fund should be re-established and modernised, with the NBR publishing clear guidelines on rebates. Uniform registration and reporting requirements should also be established for private zakat organisations rather than attempting to replace them. Competitive pressure is no threat to trust. Lack of transparency is.
Over the longer term, a national Shariah council should establish a bounded and verifiable schedule of permitted expenditure under fi sabilillah and ibn al-sabil, along with ceilings for allocations. The ibn al-sabil head should also receive a continuing appropriation for displacement responses based on the Zuhri principle: allocation according to assessed needs, with specifically named institutions responsible for delivering the funds.
The global context adds urgency to addressing this issue rather than reducing its importance. A study referenced by the UNDP estimates the annual global zakat pool at somewhere between US$200 billion and US$1 trillion. Meanwhile, the UN appeal for funding the Rohingya response in 2026 is 26 percent lower than the previous year’s. With Western aid budgets shrinking while the Muslim world remains unorganised in managing its collective wealth, these two statistics clearly define what is required in terms of policy action without needing further comment.
The problem, in the end, is not that the Quranic categories have outlived their usefulness. It is exactly the opposite. We have devoted our efforts to six of the eight categories and left idle the two that read as though they were written for the displaced person, the refugee and the child who sleeps on a road. Umar ibn Abd al-Aziz managed a proportionate allocation for stranded travellers in the second century of the Hijra. We have not yet managed to produce an audited statement of accounts.
Dr M. Kabir Hassan is a professor of finance and the Moffett Chair in the Department of Economics and Finance at LSU-New Orleans, USA. He is a Senior Fulbright Scholar, recipient of the 2016 IsDB Prize in Islamic Banking and Finance, a member of the AAOIFI Ethics and Governance Board, and Chairman of its Education Board.
Send your articles for Slow Reads to slowreads@thedailystar.net. Check out our submission guidelines for details.
Three revolutions that reshaped the world
Paradise lost and found: Rediscovering early modern Bengal
Unbound Mother: The making and remaking of Kaali in Bengal
Do great leaders make history, or does history make them?
Poison and cremation: A forensic history of colonial Bengal
Partition, Bor Porong and the Chakmas’ unfinished struggle for belonging
The young radicals who challenged 19th-century Bengal
More men are cooking. But is patriarchy leaving the kitchen?
Everyday secularism and the Bangladesh we rarely talk about